Equity Bank Uganda collected Shs16.13 billion in bancassurance premiums in the second quarter of 2026, securing an 8.77% share of Uganda’s market and ranking fourth among banks in the sector.
The performance was driven mainly by a sharp increase in life assurance premiums, which more than doubled over the year, while income from non-life insurance remained largely unchanged.
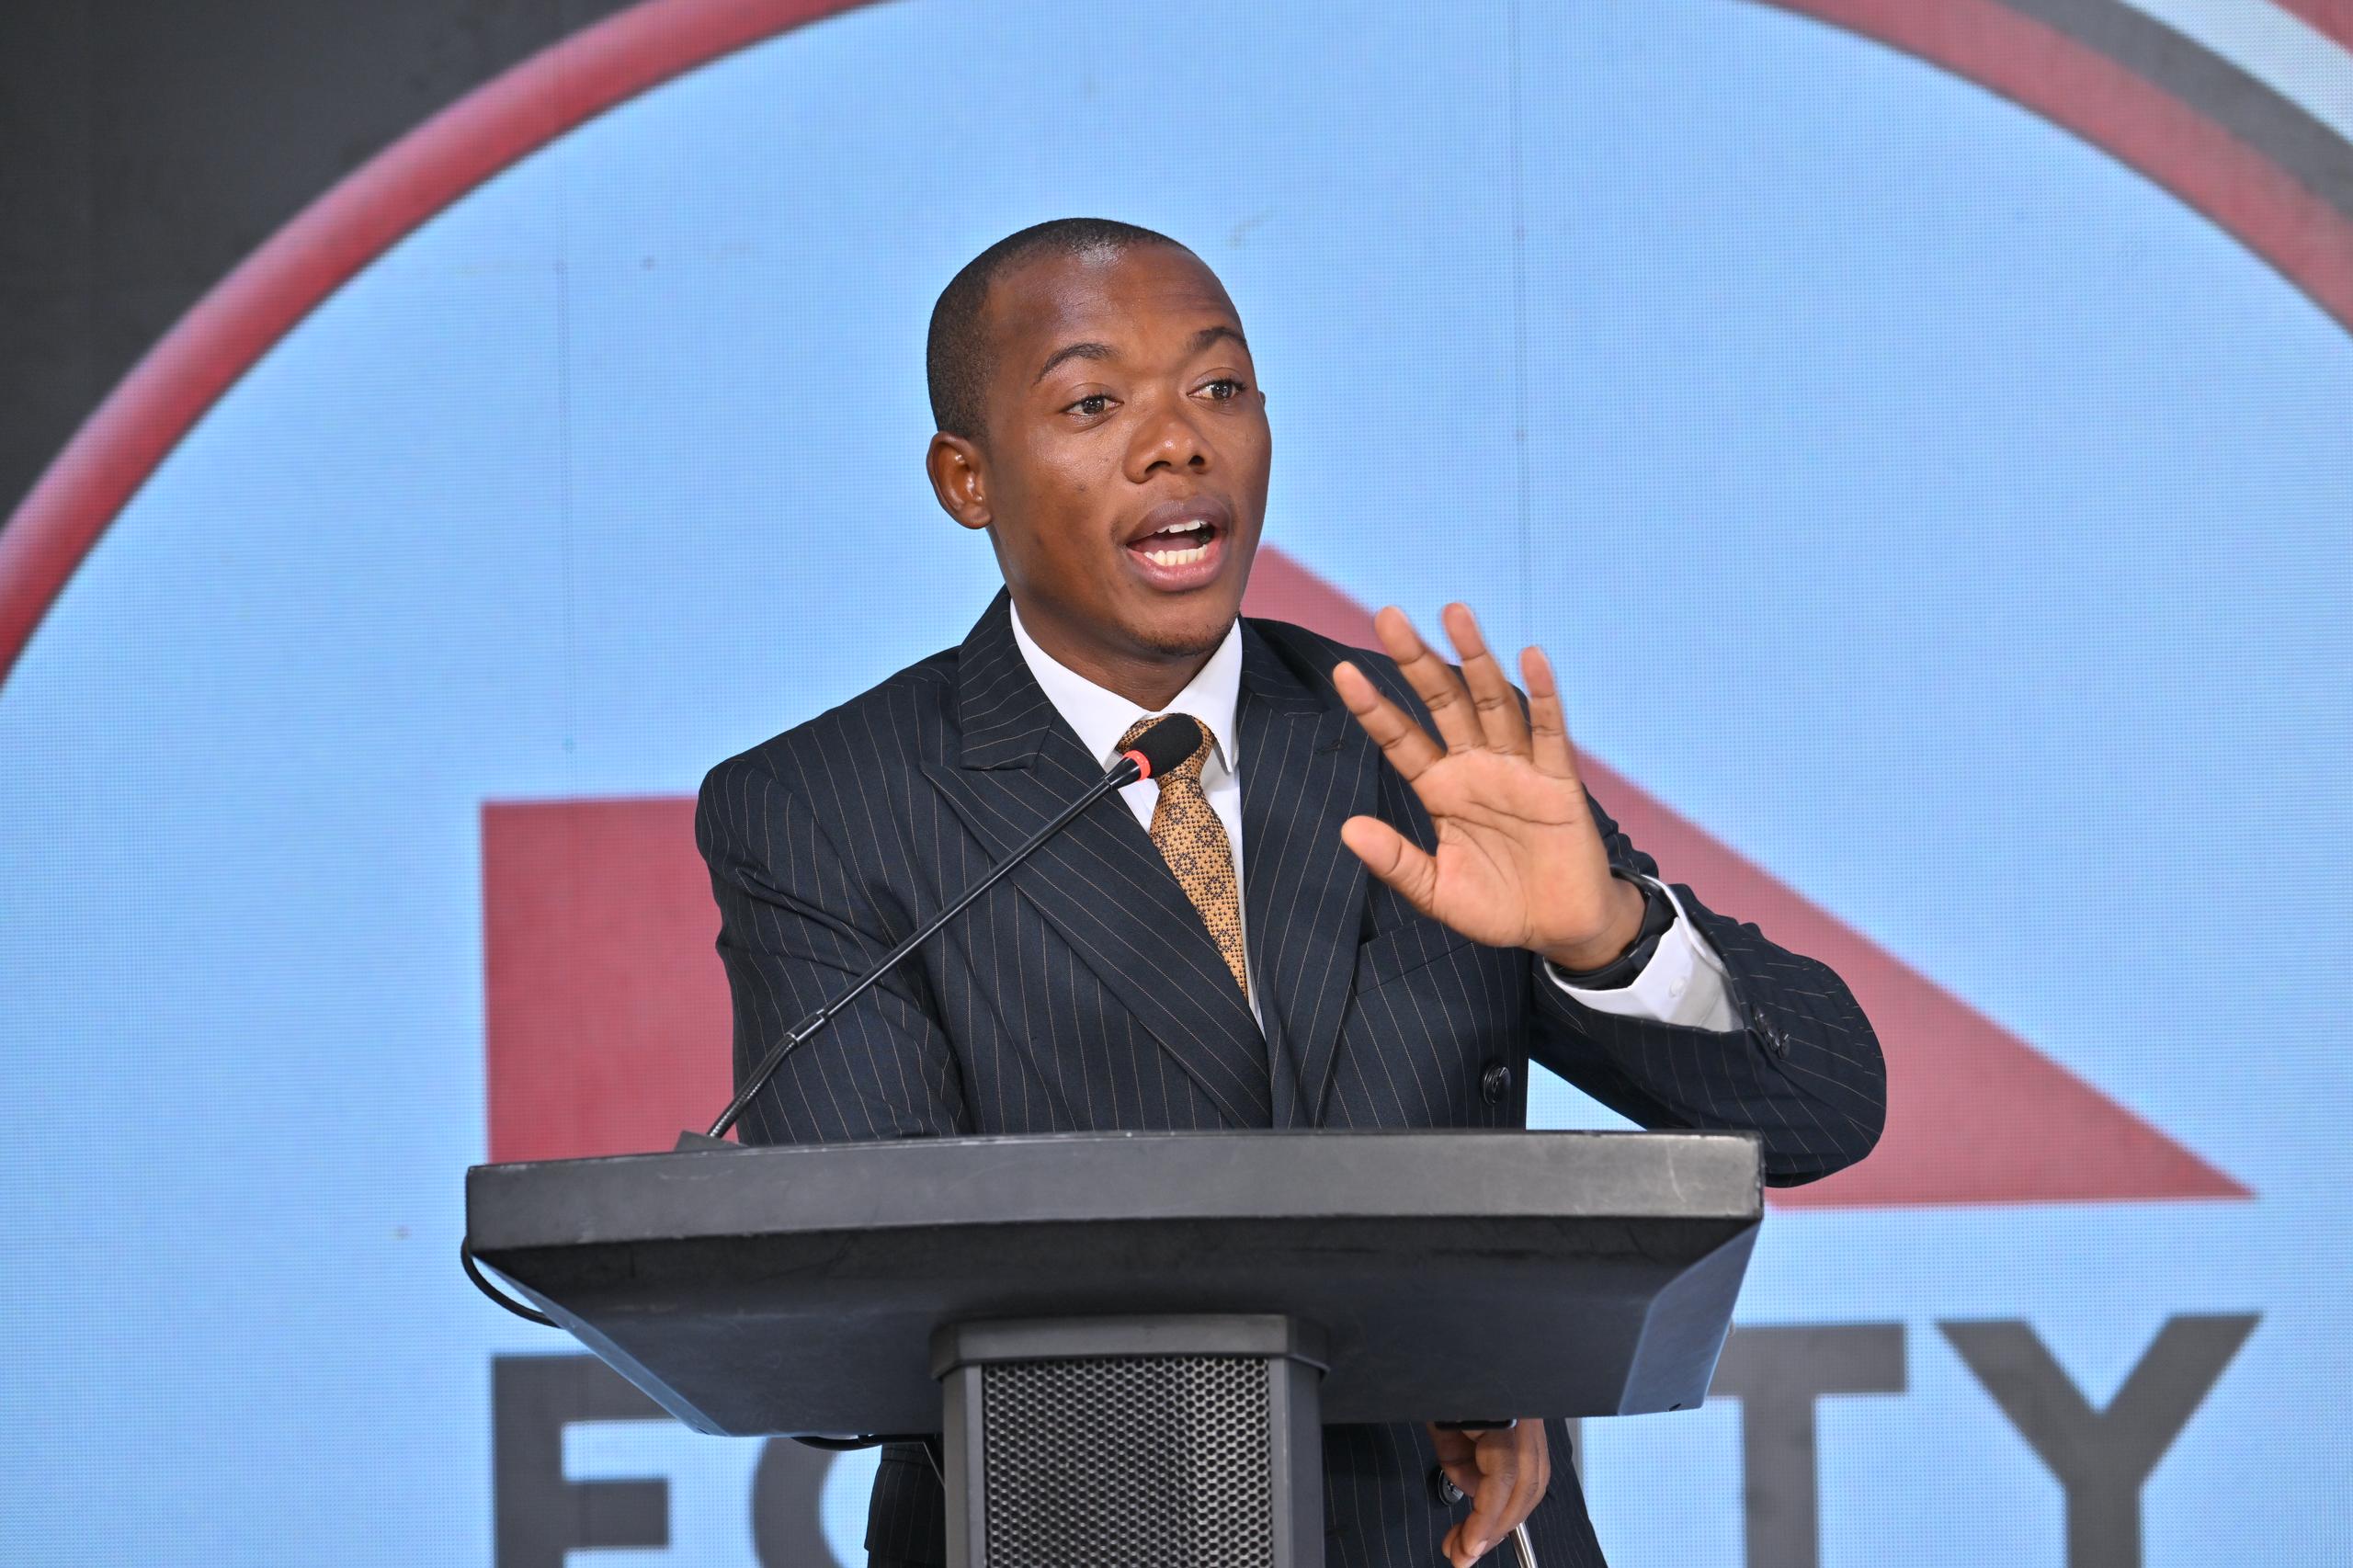
James Sserumaga, Equity Bank Uganda’s head of bancassurance, attributed the growth to staff training, improved productivity and wider access to insurance products through the bank’s branches, merchant networks and digital platforms.
Life assurance premiums rose from Shs5.73 billion in the second quarter of 2025 to Shs11.72 billion in the corresponding period of 2026, an increase of approximately 104 per cent.
However, the number of life assurance policies declined from 75,000 to 65,000 over the same period, indicating that the bank collected more premiums despite having fewer policies.
The figures suggest that the bank’s life assurance business generated more income per policy on average. This could reflect a shift towards higher-value insurance products or customers paying larger premiums, although the figures alone do not establish the precise reasons for the increase.
Sserumaga said the bank had invested in improving staff capacity and making insurance products more accessible to customers across its distribution channels.
The approach focuses on attracting new policyholders while increasing the value of business generated from existing customers.
The bank has also placed greater emphasis on policy persistency, which measures whether customers continue paying premiums and maintaining their insurance cover over time.
According to Sserumaga, dedicated customer engagement teams follow up with policyholders to encourage timely premium payments and renewals. The bank says these efforts have helped strengthen insurance income.
Maintaining active policies is important to insurance providers because customers who continue paying premiums help sustain income over the life of their cover.
While life assurance recorded strong growth, the bank’s non-life insurance business experienced a slight decline in premiums.
Non-life premiums fell from Shs4.45 billion in the second quarter of 2025 to Shs4.41 billion in the same period of 2026.
Despite the marginal drop in premiums, the number of non-life policies increased from 659 to 839, suggesting that the bank issued more policies but generated slightly less premium income from the segment.
The bank linked the slowdown partly to changes in its lending portfolio.
Non-life insurance products associated with secured lending, including insurance for property used as loan collateral, have traditionally contributed to premium income.
However, the growing proportion of unsecured loans has reduced demand for some insurance products linked to secured borrowing.
Sserumaga said the bank was exploring products such as micro-medical insurance to make insurance more accessible to a wider section of the population.
Microinsurance generally provides affordable cover designed around the needs and financial capacity of people with lower incomes, potentially helping more Ugandans access protection against medical costs and other financial risks.
Equity Bank Uganda’s second-quarter results highlight the growing contribution of life assurance to its bancassurance business, while the decline in non-life premiums points to the need to diversify products and adapt to changes in lending patterns.