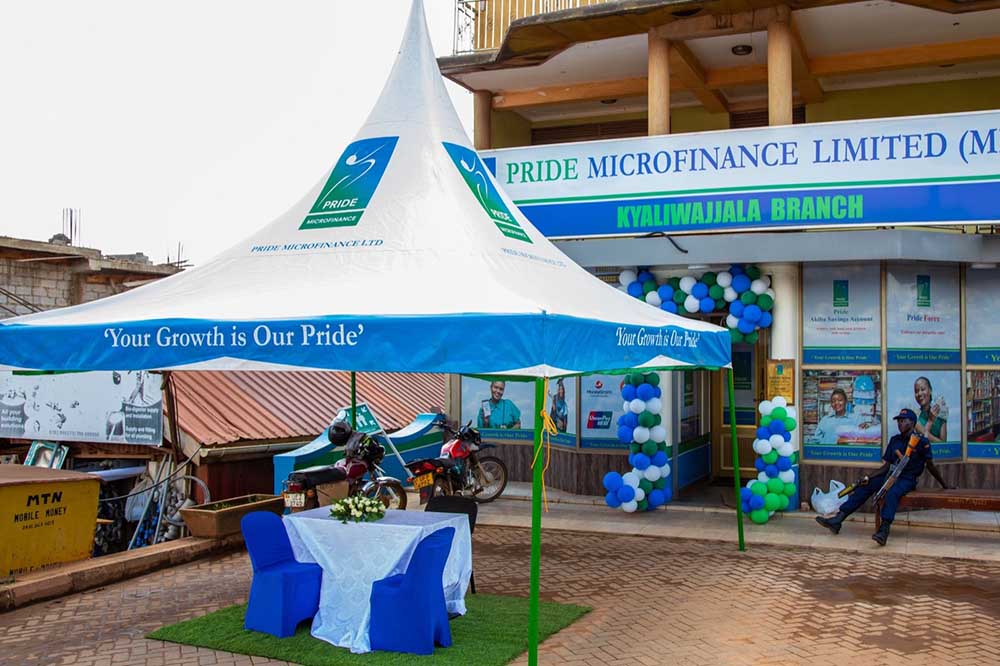
Pride Microfinance (now Pride Bank) lost a court battle over the sale of a customer’s land after the High Court found that it rejected attempts to clear an outstanding loan of Shs 2.9m before the repayment deadline, then proceeded to sell the property used as security.
Justice Stephen Mubiru said the microfinance institution frustrated the borrower’s attempts to redeem the property, failed to give her proper notice of the sale, and sold the land at a price far below its assessed value.
The dispute involved Godfrey Bihemaiso, whose mother, Adyeeri Mbabazi, borrowed Shs8 million from Pride Microfinance in November 2006, using his land at Lukuli in Kampala as security.
Mbabazi obtained the loan using a power of attorney her son, who owned the land, granted her.
The loan was supposed to be repaid within 12 months at an annual interest rate of 25%, and Mbabazi was required to make monthly payments of approximately Shs833,350.
The land was valued at Shs60 million, with a forced sale value of Shs45 million, before the loan was granted.
Mbabazi initially serviced the loan but started experiencing difficulties in making payments in March 2007 after falling ill.
By October 2007, the outstanding loan balance stood at approximately Shs2.97 million, which was supposed to be cleared by December 2007, when the loan period would expire.
When Mbabazi realised that she was struggling to meet the repayment obligations, she informed her guarantor, Raphael Mahunge, who stepped in to help clear the outstanding balance.
Mahunge started making payments towards the loan, depositing Shs500,000 on August 1, 2007, and another Shs1 million on August 15, 2007.
However, trouble started when Mahunge returned to Pride Microfinance to deposit another Shs1.7 million towards clearing the outstanding balance.
Instead of receiving the money, Pride Microfinance’s staff directed him to its legal department, where he was informed that the institution had already foreclosed on the property and that it was being sold.
Mbabazi’s lawyers subsequently wrote to Pride Microfinance on October 22, 2007, protesting against the rejection of the payment.
Bihemaiso also told the court that he had travelled abroad for further studies shortly after authorising his mother to use the land as security.
When he returned to Uganda on October 15, 2007, he was shocked to find another woman claiming to have purchased the property from Pride Microfinance.
He told the court that he had never been allowed to redeem his land and believed that the loan period had not yet expired.
Pride Microfinance, however, maintained that Mbabazi had defaulted on her loan obligations and that the institution had made several attempts to recover the money.
It argued that it issued demand notices in May, June and August 2007 but Mbabazi either refused to receive them or could not be traced.
It further told the court that it advertised the property for sale in the Red Pepper newspaper on August 15, 2007, and that the highest bidder eventually purchased it for Shs20 million.
The property was bought by Annet Mary Nabaggala, an estate agent, who told the court that she had seen the advertisement, inspected the property, and submitted her bid.
She said Pride Microfinance accepted her offer and she completed the transaction on September 26, 2007.
The financial institution maintained that it was legally entitled to sell the property because the mortgage agreement allowed it to realise the security without going to court if the borrower defaulted.
However, Mbabazi insisted that the sale was irregular because the lender had rejected payments while the guarantor was actively trying to clear the loan.
The dispute first went before the Mengo Chief Magistrate’s Court, where the court ruled in favour of Mbabazi and Bihemaiso on November 7, 2013.
The court found that Pride Microfinance had denied the borrower a chance to redeem her property by refusing to receive the outstanding payments.
It also questioned why the property, which had been valued at Shs60 million and had a forced sale value of Shs45 million, was sold for only Shs20 million.
It declared the sale null and void, permanently restrained Pride Microfinance from interfering with the respondents’ peaceful enjoyment of the property and awarded them Shs10 million in general damages.
Dissatisfied, Pride Microfinance appealed to the High Court, arguing that the chief magistrate had wrongly declared the sale unlawful and unfairly attributed fraud to the institution.
During the appeal, it argued that once Mbabazi defaulted on her instalments, the entire outstanding loan became due, meaning she could no longer rely on the original 12-month repayment period.
The institution further defended the sale price of Shs 20 million, saying it was determined by market forces and that several interested buyers had inspected the property before Nabaggala emerged as the highest bidder.
But Mbabazi and Bihemaiso maintained that the outstanding balance was only Shs2.9 million and that the guarantor had taken responsibility for clearing it.
They also argued that Pride Microfinance had deliberately frustrated the attempts to pay off the loan to defeat the owners’ right to recover their property.
Shonubi loses bid to have his law firm’s bank account unfrozen in Shs 100m dispute
In his judgment, Justice Mubiru agreed with Mbabazi and Bihemaiso, emphasising that lenders have a duty to act fairly and in good faith when exercising their powers to sell mortgaged property.
He noted that even though the law at the time did not strictly require a statutory demand notice before the sale, Pride Microfinance still had a common law duty to give the borrower fair notice and a reasonable opportunity to redeem the property.
He observed that the evidence showed Mbabazi had never personally received any of the demand notices.
“The guarantor only received copies of the notices when he went to the bank to pay the outstanding balance, after the sale had already been concluded,” Justice Mubiru stated.
He further explained that the right of a borrower to redeem mortgaged property is a fundamental principle of mortgage law and cannot simply be taken away because of a payment default.
Citing an earlier decision in Erisa Wamala v Musa Musoke, Justice Mubiru noted that a mortgage is “always security and not a charge created by the mortgage deed on the repayment of the loan sum advanced.”
He added that equity allows a borrower to redeem mortgaged property even after the agreed repayment date has passed.
He was particularly concerned that Pride Microfinance sold the land on September 26, 2007, about three months before the loan repayment period ended, while the guarantor was still making payments.
“When the guarantor attempted to deposit Shs. 1,700,000/= on 19th October 2007 (or 20th October 2007 per his testimony), the payment was rejected, and he was referred to the legal department, where he was informed the property had already been sold,” he stated.
Shonubi loses bid to have his law firm’s bank account unfrozen in Shs 100m dispute
Justice Mubiru said the lender’s argument that the entire debt had been recalled following default could not override the borrower’s right to redeem the property.
He also questioned the sale price, noting that the property had been valued at Shs45 million as its forced sale value but was sold for only Shs20 million.
Justice Mubiru observed that the bailiff who handled the sale had not been given a valuation report at the time of the transaction and that no fresh valuation had been conducted.
He said the difference between the forced sale value and the actual selling price raised serious questions about Pride Microfinance’s conduct.
He also found that although the property had been advertised for sale by public auction, it was eventually sold through a private treaty at Pride Microfinance’s branch offices.
He explained that a lender cannot simply switch from a public auction to a private sale without obtaining the written or explicit consent of the property owner and other affected parties.
Even where a private sale is permitted, the lender must ensure that the property is properly marketed to attract potential buyers and secure the best possible price.
Justice Mubiru further upheld the finding that the lender had not adequately accounted for the proceeds of the sale.
Although Nabaggala purchased the property for Shs20 million, only Shs14 million was credited to Mbabazi’s account, leaving Shs6 million unexplained.
He also noted that the two loan account statements presented by Pride Microfinance contained inconsistencies that the institution had failed to satisfactorily explain.
In the final decision, Justice Mubiru dismissed Pride Microfinance’s appeal, meaning the earlier judgment in favour of Bihemaiso and Mbabazi remains in force.
The court awarded the respondents the costs of both the original case and the appeal.